

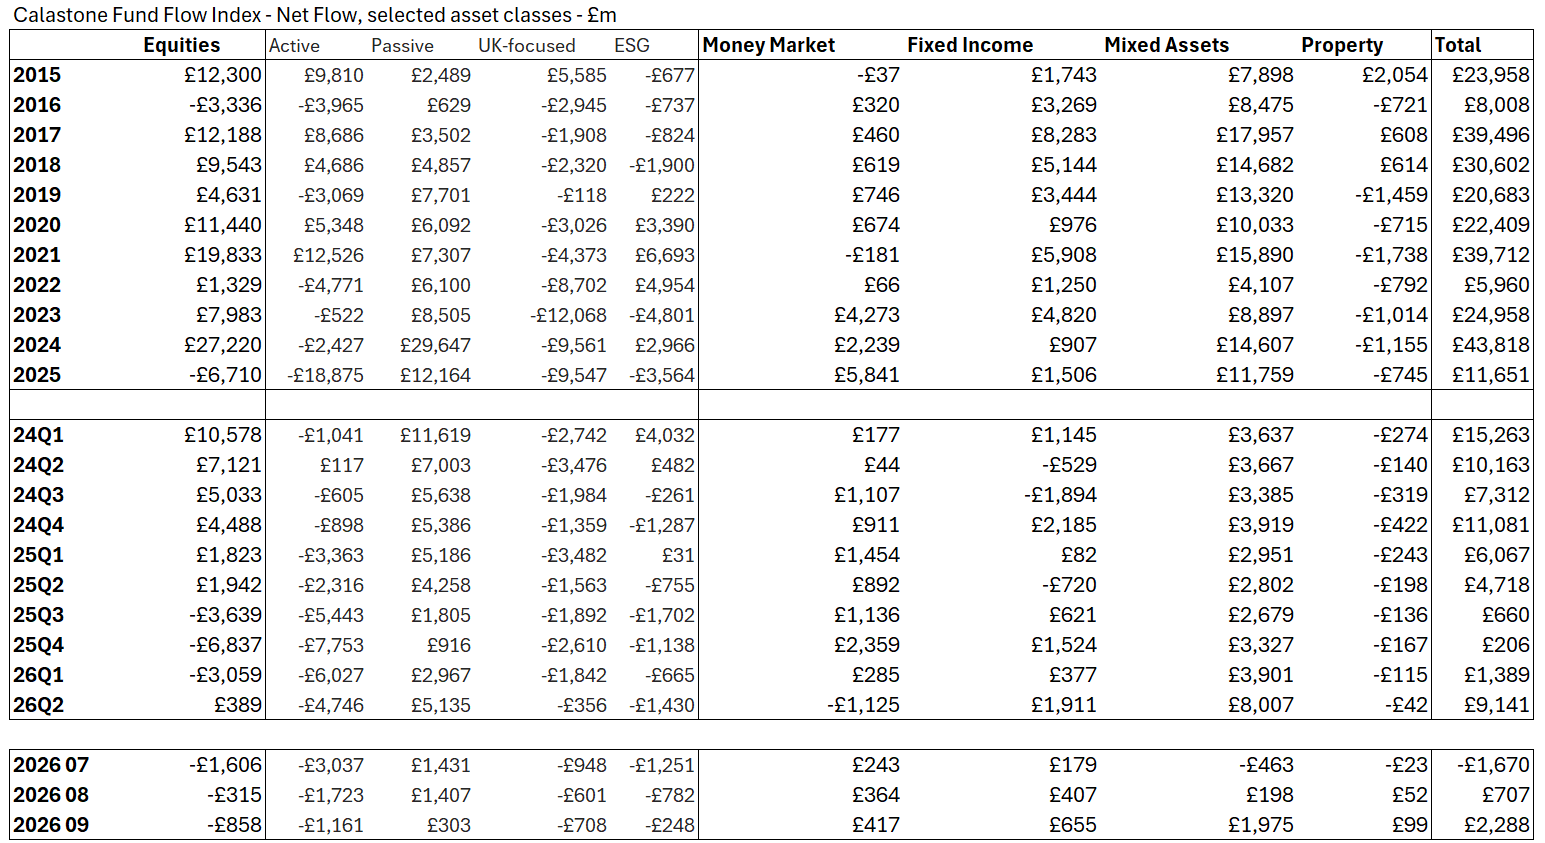
UK investors continued to retreat from equity funds in September, withdrawing a net £858m, the 15th month of outflows in the last 16, according to the latest Fund Flow Index from Calastone, the largest global funds network. Year-to-date, equity funds have suffered outflows of £5.45bn.
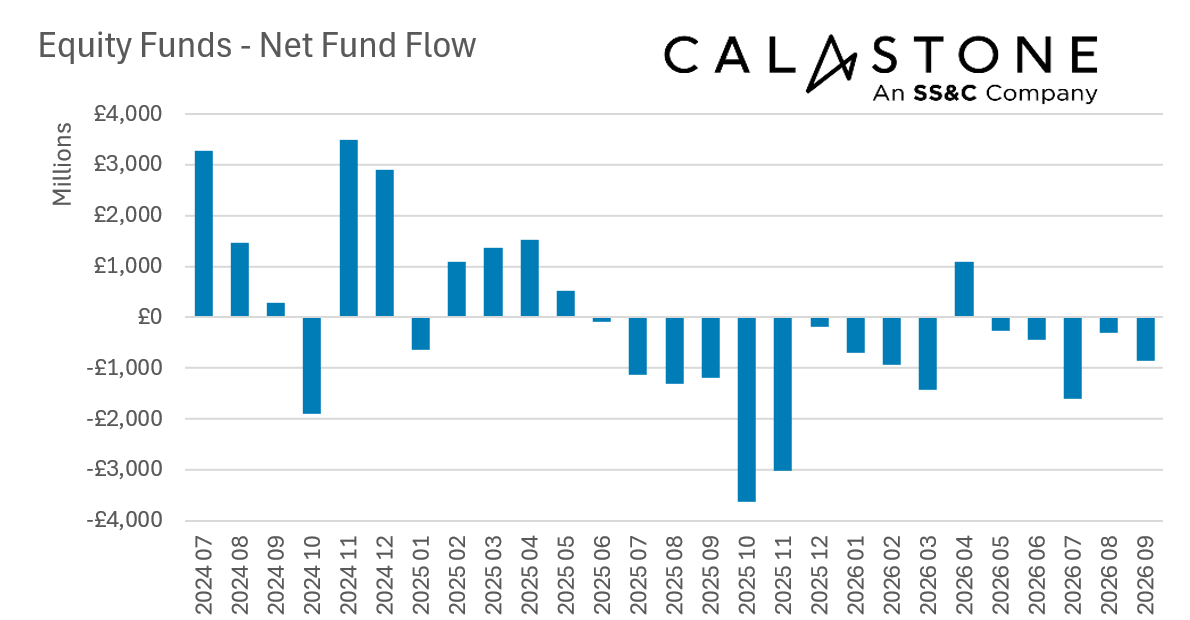
UK-focused equity funds remain firmly on the sell list. Investors withdrew £708m during the month, marking the 63rd month of outflows in the last 65. UK-focused funds have shed £47.7bn in that period.
The caution spread well beyond the domestic market, however. North American equity funds shed £124m, their largest outflow since November 2025, while Asian equity funds lost £371m, their second-worst month on record[1]. European, Japanese, Chinese and sector-focused equity funds all suffered net selling too.
There were two notable exceptions. Global equity funds attracted £410m, while emerging-market funds took in £133m.
Investors turn to bonds and cash
Fixed income continued to attract UK investors. Bond funds enjoyed net inflows of £655m in September, taking the year-to-date total to £3.53bn.
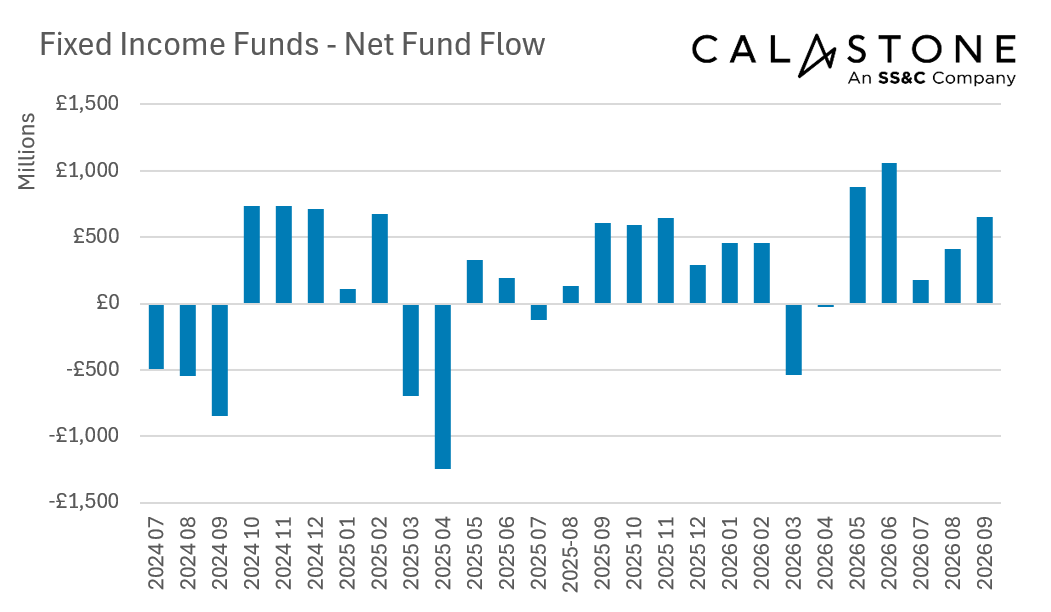
High-yield funds were the clear favourite, attracting £421m. The sector has been the most popular bond category in the last two years, with £3.17bn of net purchases (46% of total bond inflows). Sovereign bond funds also returned to favour, taking in £116m. The inflow comes despite a turbulent period for government bond markets.
Money market funds were a major beneficiary of investors’ caution. They attracted £417m in September, their largest inflow since November.
Edward Glyn, head of global markets at Calastone, said: “Investors are nervous and this is making them very picky. Equities overall remain firmly out of favour, particularly UK stocks, despite relatively resilient market performance. High share prices, surging bond yields and significant geopolitical and inflation concerns mean investors have plenty of reasons to question how much equity risk they want to carry. Inflows to emerging markets suggest a search for diversification – they offer exposure to economies and valuations that look very different from the heavily owned US market, for example.
“September’s global bond upheaval has a range of causes – rising energy prices and therefore inflation fears, weak government finances and competition from corporate borrowers. The resulting higher yields mean losses for existing bondholders, but they also increase the income available to investors buying at today’s prices, making bonds more attractive to new money.
“Money market funds complete the picture. Investors can currently earn a meaningful return on cash without any duration or equity-market risk – a safe haven.
“All this shows that investors still want returns, but they are demanding more compensation for taking risk.
“This month’s Budget is also likely to be a factor in driving rising outflows from equities. Speculation about higher taxes means some investors will be taking profits now.”
Methodology
Calastone’s Fund Flow Index (FFI) is the most widely followed, most timely, and most comprehensive tracker of fund flows in the UK. Because it relies on real trading data by investors, rather than survey opinion, it is also the most accurate.
The FFI analyses millions of buy and sell orders in individual funds every month from millions of UK-based investors. More than 85% of all UK fund flows by value pass across Calastone’s network. To avoid double-counting, however, the analyst team excludes funds of funds. Totals are scaled up for Calastone’s market share.
Net fund flows are the difference between the value of investor buy orders and investor sell orders. The value of buy orders and the value of sell orders are both very large – the net flow is typically very small in comparison to this large amount of trading activity.
Calastone only measures orders from UK-based investors into funds domiciled in the UK. Note that this has nothing to do with where the underlying assets are invested – a UK-domiciled fund may invest in Japanese equities, Australian fixed income, a global portfolio of mixed assets, or just UK equities. The fund sector information breaks this down in detail.
Calastone uses the FE Fundinfo dataset to assign characteristics such as fund sector, or active v passive to each fund. Before December 2024 Calastone used Lipper for this function. Calastone has restated all historic data with the new FE Fundinfo data to ensure consistency. The new FE FundInfo provides enhanced coverage, and now includes many funds that are not classified by Lipper. The new FFI is therefore even more comprehensive than before, and the historic data now reflects this improvement. Calastone’s analysts do not judge there to be any material differences in the trends revealed using FE FundInfo classifications v Lipper, though there are minor points of detail that differ in individual months.
Calastone also calculates an index value to enable comparison between different asset classes and fund sectors of different sizes. A reading of 50 indicates that buy and sell orders are equal in value. A reading above 50 means capital is flowing in and a reading below 50 means it is flowing out. In other words, a net inflow of £1m would score much more highly if it is the difference between, say £10m of buys and £9m of sells than if it was the difference between £100m of buys and £99m of sells.
[1] Worst month was £382.9m outflow in April 2026