

UK investors continued to sell down equities in August, according to the latest Fund Flow Index from Calastone, the largest global funds network.
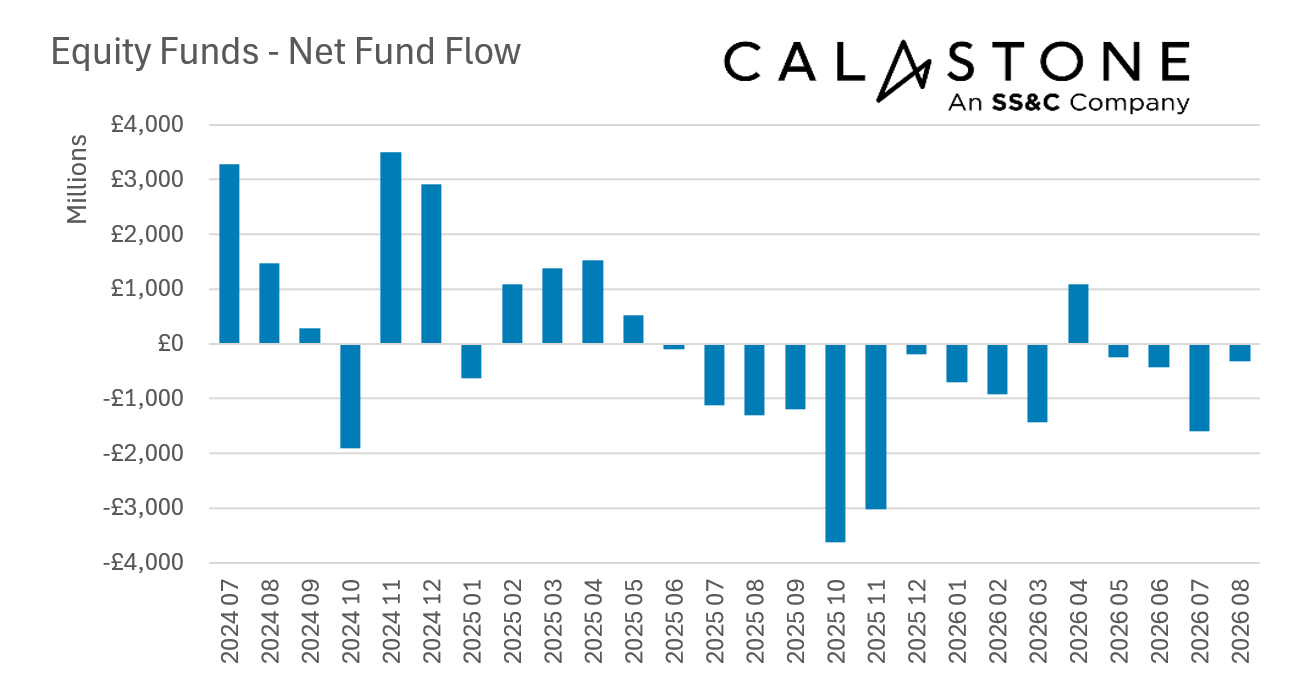
Equity funds suffered net outflows of £315m during the month, marking the fourth consecutive month of net selling and the 14th month of outflows in the last 15.
Although August’s outflow was considerably smaller than the £1.61bn withdrawn in July, investors have now sold down £15.16bn from equity funds since June 2025.
UK and European equities bear the brunt
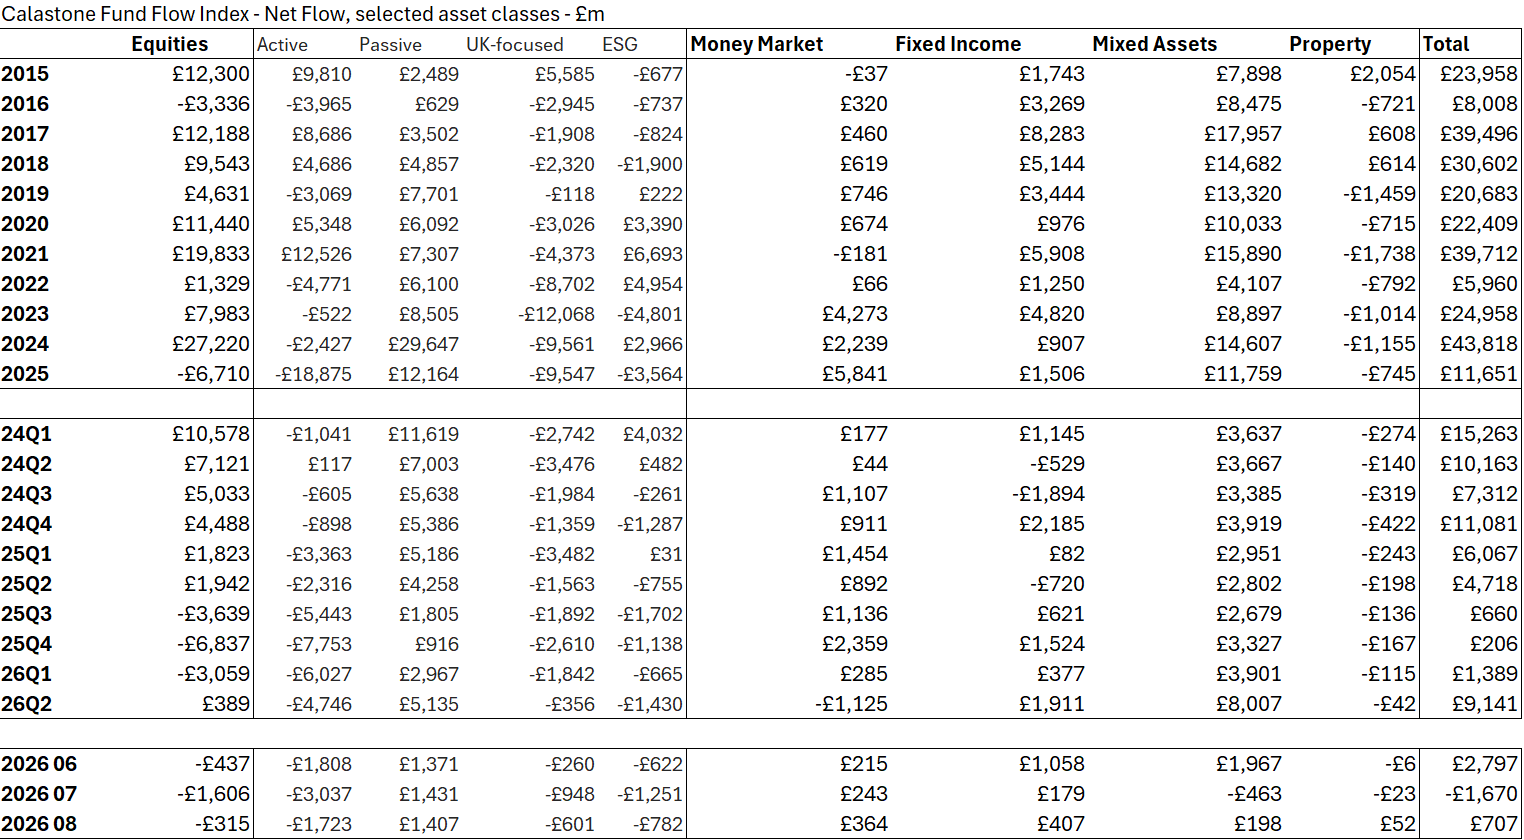
August’s selling was concentrated in funds focused on UK (-£601m) and European equities (-£145m) while specialist sector funds also suffered withdrawals (-£52m). North American funds saw outflows of £3m. This was the first withdrawal for this last sector since November 2025 but was tiny at just 0.06% of the combined £4.9bn of buy and sell orders.
Investors continue to favour fixed income
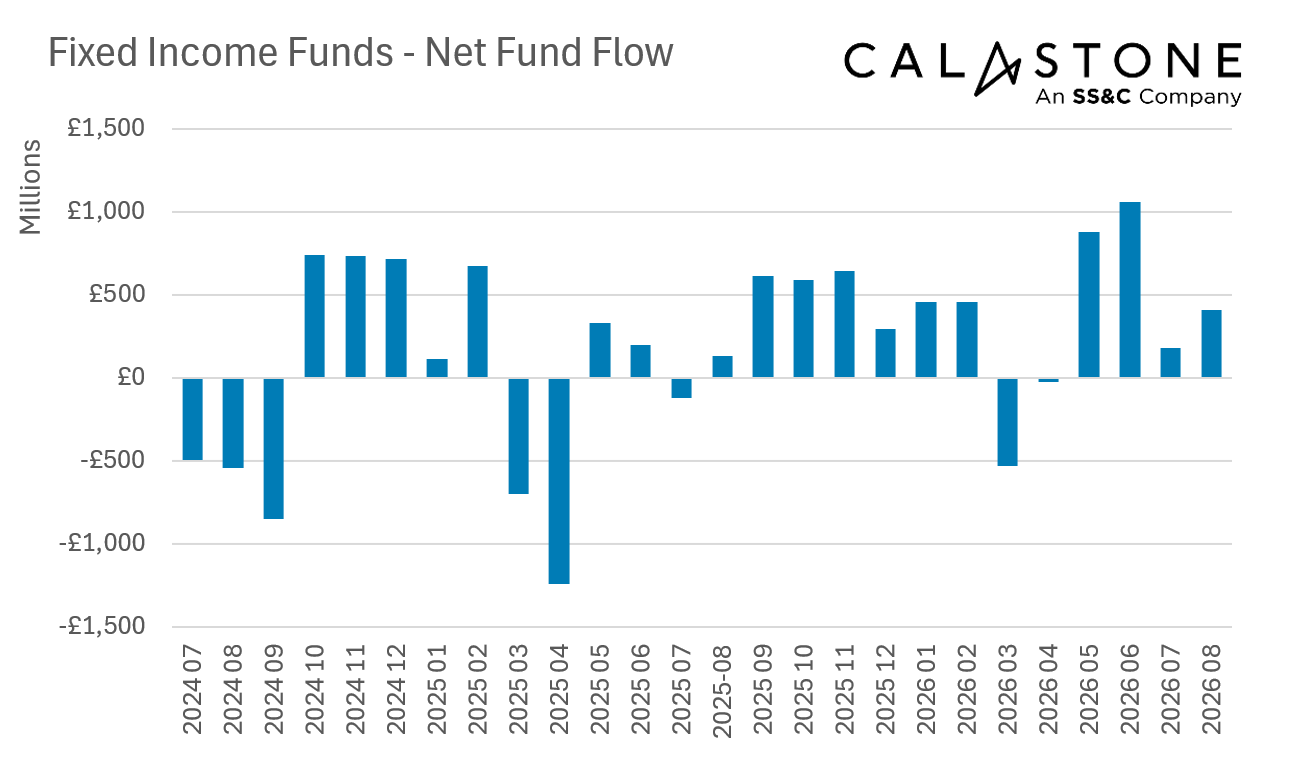
Bond funds attracted £407m of new capital in August, the fourth consecutive month of inflows, and broadly in line with the average over the last 12 months.
Safe-haven money market funds saw a more pronounced increase in demand. Investors added a net £364m in August, double the 12-month average and their largest inflow since November.
Together, bond and money market funds attracted £771m of net new capital during the month, as investors opted for assets offering income, liquidity and reduced downside risk. Since equity market outflows began in June 2025, money market and bond funds have absorbed £8.7bn.
Edward Glyn, head of global markets at Calastone, said: “Such prolonged outflows from equity funds are incredibly rare. There is a huge built-in bias towards fund inflows as UK households add to their savings over time – and equity funds have traditionally been big beneficiaries.
“Investors aren’t panicking, but they are stubbornly refusing to chase equity markets higher. August’s outflow was much smaller than July’s, but the pattern is now well entrenched. With markets near record highs, investors may have reservations about where equities go from here.
“Continuous Budget speculation is adding to that caution. If investors believe capital gains and pension tax breaks are in the firing line, some of them have a reason to act now rather than risk delay.
“Cash is also doing more of the talking. Money market funds have had their strongest month since November, while bond inflows continue to attract healthy sums. When investors can earn a decent return without taking equity risk, there is much less pressure to chase the market. They can afford to sit on the sidelines and wait for a better reason to buy.”
Methodology
Calastone’s Fund Flow Index (FFI) is the most widely followed, most timely, and most comprehensive tracker of fund flows in the UK. Because it relies on real trading data by investors, rather than survey opinion, it is also the most accurate.
The FFI analyses millions of buy and sell orders in individual funds every month from millions of UK-based investors. More than 85% of all UK fund flows by value pass across Calastone’s network. To avoid double-counting, however, the analyst team excludes funds of funds. Totals are scaled up for Calastone’s market share.
Net fund flows are the difference between the value of investor buy orders and investor sell orders. The value of buy orders and the value of sell orders are both very large – the net flow is typically very small in comparison to this large amount of trading activity.
Calastone only measures orders from UK-based investors into funds domiciled in the UK. Note that this has nothing to do with where the underlying assets are invested – a UK-domiciled fund may invest in Japanese equities, Australian fixed income, a global portfolio of mixed assets, or just UK equities. The fund sector information breaks this down in detail.
Calastone uses the FE Fundinfo dataset to assign characteristics such as fund sector, or active v passive to each fund. Before December 2024 Calastone used Lipper for this function. Calastone has restated all historic data with the new FE Fundinfo data to ensure consistency. The new FE FundInfo provides enhanced coverage, and now includes many funds that are not classified by Lipper. The new FFI is therefore even more comprehensive than before, and the historic data now reflects this improvement. Calastone’s analysts do not judge there to be any material differences in the trends revealed using FE FundInfo classifications v Lipper, though there are minor points of detail that differ in individual months.
Calastone also calculates an index value to enable comparison between different asset classes and fund sectors of different sizes. A reading of 50 indicates that buy and sell orders are equal in value. A reading above 50 means capital is flowing in and a reading below 50 means it is flowing out. In other words, a net inflow of £1m would score much more highly if it is the difference between, say £10m of buys and £9m of sells than if it was the difference between £100m of buys and £99m of sells.